

How to Finance a Mazda for Your Next Drive
A Mazda should feel right long after the test drive, not just when you first settle into the driver’s seat. Learning how to finance a Mazda starts with matching the vehicle, payment structure, and ownership plan to your real life: school runs in Palm Desert, weekend miles to Idyllwild, commutes across the Coachella Valley, or open-top drives in an MX-5 Miata.
The best financing choice is rarely the one with the lowest-looking monthly payment alone. It is the one that lets you drive a vehicle you trust, keeps the terms clear, and supports your household’s plans for the years ahead.
Start With the Mazda That Fits Your Life
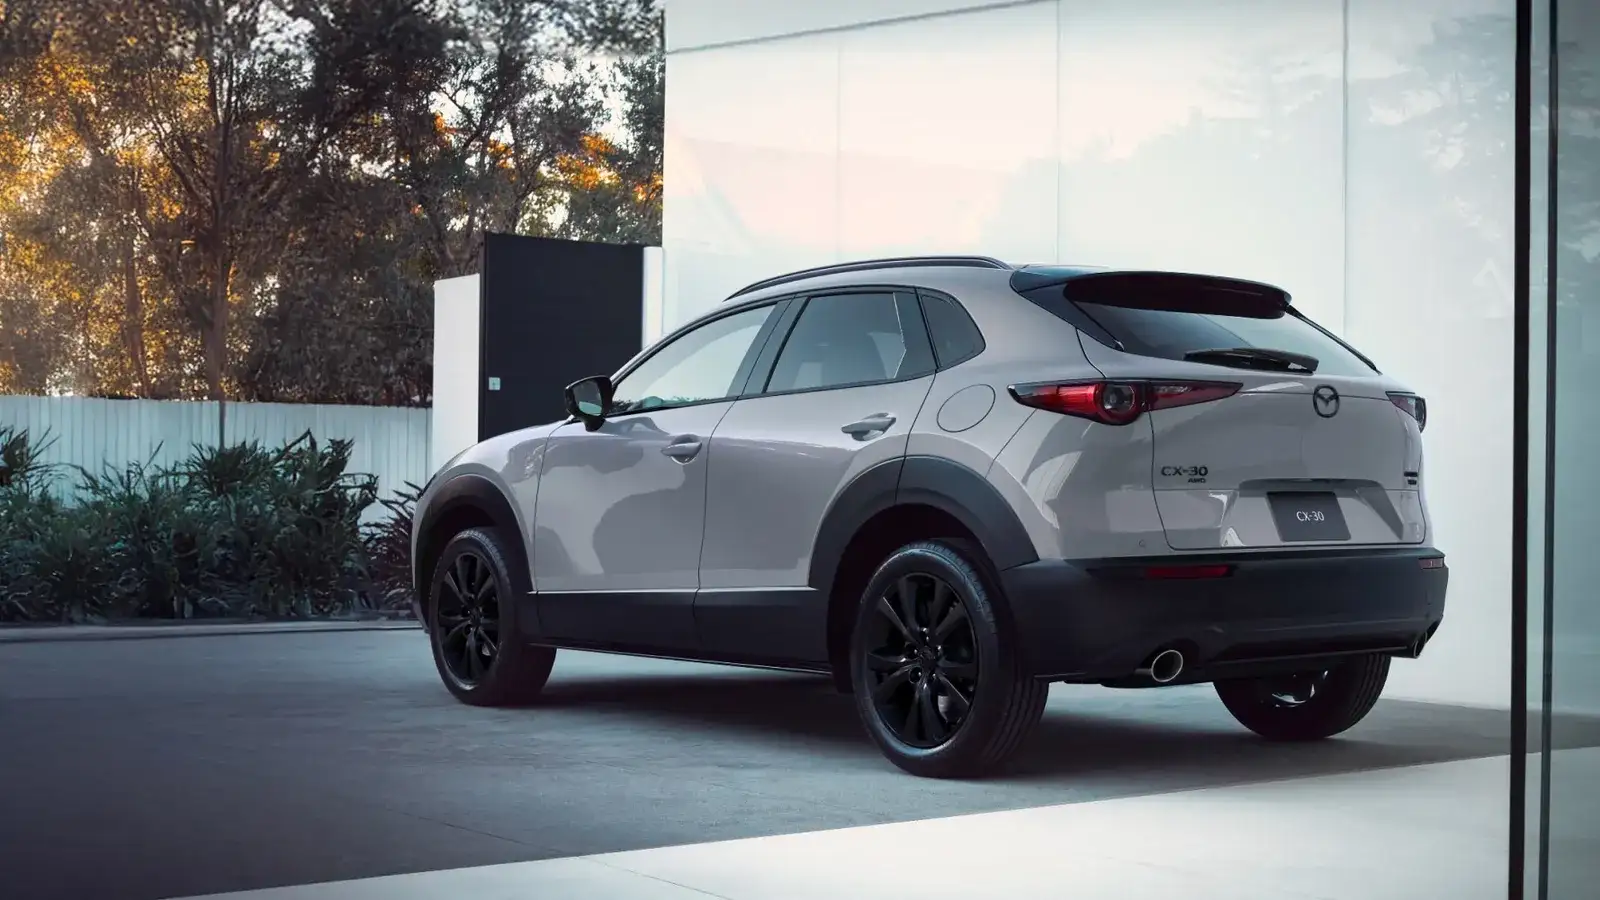
Financing is easier when you know what you need the vehicle to do. A compact CX-30 can be a smart fit for a driver who wants elevated seating and city-friendly dimensions. The CX-5 remains a natural choice for many small families, while the more ruggedly styled CX-50 may appeal to shoppers who plan to carry outdoor gear or take regular road trips. For growing families, the CX-70 and CX-90 offer more room and available electrified powertrain options.
Your choice affects more than the vehicle itself. A larger SUV, a higher trim level, available all-wheel drive, and an electrified powertrain can all change the total financing picture. That does not make one option better than another. It simply means your payment should be considered alongside your expected mileage, insurance, fuel or charging habits, and how long you plan to keep the vehicle.
If you are weighing a new Mazda against a Mazda Certified Pre-Owned model, consider the ownership experience rather than assuming new is always the only answer. New vehicles may offer the latest features and powertrains, while Mazda Certified Pre-Owned vehicles can be especially appealing to value-focused shoppers who want a carefully inspected vehicle and added confidence. Ask to compare both options using similar terms so the difference is easy to understand.
How to Finance a Mazda: Know Your Main Options
Most buyers choose between an auto loan and a lease. Both can work well, but they suit different drivers.
With an auto loan, you borrow money to purchase the Mazda and make scheduled payments over an agreed term. Once the loan is paid off, you own the vehicle outright. This is often a strong route for shoppers who expect to keep their Mazda for many years, drive more than average, or want the flexibility to customize their ownership experience without lease mileage limits.
A lease is designed around using a new vehicle for a set period and estimated mileage. At the end of the term, you typically return the vehicle, purchase it if that option is available, or move into another vehicle. Leasing can make sense for shoppers who enjoy driving a newer Mazda every few years, want to stay within a predictable mileage range, and prefer a shorter commitment. It may be less attractive if your annual mileage is unpredictable or you want to build long-term ownership equity.
There is no universal winner. A Palm Springs resident who takes occasional local trips may be comfortable with a lease, while an Indio family that regularly drives throughout Southern California may prefer the freedom of ownership. Be upfront about how you actually drive, not how you hope to drive.
Prepare Before You Apply
A little preparation can make your financing conversation more productive and less stressful. Start by reviewing your monthly budget. Think beyond the vehicle payment to include insurance, fuel, charging if applicable, maintenance, registration, and any accessories you may want.
Next, review your credit report for accuracy. Your credit history helps lenders evaluate the terms they can offer, but it is not the only factor. Income, existing debt, down payment, loan term, and the vehicle itself can matter as well. If you have questions about credit challenges or limited credit history, ask early. A good finance conversation is built on facts, not judgment.
It also helps to gather a few common documents before applying for financing. These may include a valid driver’s license, proof of income, proof of residence, insurance information, and details on a trade-in if you have one. Requirements can vary, so confirm what applies to your situation before your visit.
A down payment can reduce the amount financed and may improve the payment structure, but the right amount depends on your savings and other priorities. Avoid draining an emergency fund just to make a larger down payment. The goal is a healthy overall financial decision, not simply the shortest possible payment conversation.
Look at the Full Terms, Not Just the Payment
A lower monthly payment can be useful, but it can also result from a longer loan term. Longer terms may help create more room in a monthly budget, yet they can increase the total finance charge and may leave you owing more than the vehicle’s value for longer.
Ask for a clear review of the annual percentage rate, length of the loan or lease, total amount financed, expected payment schedule, and any applicable fees. If you have a trade-in, make sure you understand its value separately from the financing terms. Keeping those conversations distinct makes it easier to see the complete picture.
For leases, pay particular attention to the mileage allowance, wear-and-use expectations, and end-of-term choices. For loans, ask how extra payments work and whether there is any prepayment penalty. Clear answers today help prevent surprises later.
Use a Trade-In Thoughtfully
A trade-in can simplify your purchase and potentially reduce the amount you need to finance. Before bringing it in, remove personal items, bring available service records, and know the payoff amount if you still have a loan on the vehicle.
If the payoff is higher than the trade-in value, that difference is sometimes called negative equity. Rolling it into a new loan may be possible, but it raises the amount financed. This is a situation where slowing down and reviewing the numbers carefully matters. Depending on your budget and vehicle needs, it may be better to make additional payments on the current loan or choose a vehicle and term that keep the new obligation manageable.
Safety and Value Belong in the Financing Conversation
For many Coachella Valley households, the value of a Mazda is not limited to design or driving feel. Safety technology, thoughtful cabin design, and long-term service support can matter just as much when you are choosing a vehicle for family members.
Check safety information for the exact model year and trim you are considering. IIHS ratings and Consumer Reports evaluations can change by vehicle year, equipment, and available safety features. Features such as blind spot monitoring, adaptive cruise control, lane support, and rear cross-traffic alert may be available or standard depending on the Mazda you choose. A product specialist can help you compare the equipment that matters most to your family.
For hybrid- and PHEV-curious shoppers, be equally practical about charging. Consider whether you can charge at home, how often you take longer trips, and whether your daily driving pattern will let you benefit from electrified capability. A PHEV can be an excellent fit, but only when it matches the way you will use it.
Ask Questions Until the Plan Feels Clear
You deserve time to understand the agreement before signing. Ask what happens if you want to pay ahead, what protection products are available and optional, and how service planning may fit into your ownership experience. Optional products can offer peace of mind for some buyers, but their value depends on your driving habits, coverage needs, and budget.
At Palm Springs Mazda, the goal is to help you make a choice you can feel good about well beyond delivery day. Whether you are considering a Mazda3, a family-ready SUV, a Mazda Certified Pre-Owned vehicle, or an electrified CX-90, bring your questions, your budget, and an honest picture of your driving needs. You can then explore available inventory, apply for financing, and choose a path that keeps you driven forward with confidence.
Frequently Asked Questions
Does Mazda offer special financing rates?
Mazda periodically offers special APR financing on select new models through Mazda Financial Services for qualified buyers. Offers change often, vary by model and term, and may not be combinable with other incentives. Check the current Mazda offers before you visit Palm Springs Mazda, and ask the finance team to compare a special rate against any available cash incentive.
Will shopping several lenders hurt my credit?
Each application can create a credit inquiry, but common scoring models usually count multiple auto loan inquiries within a short shopping period as one. That means you can compare a credit union offer with dealer-arranged financing without much added impact, as long as you keep your shopping focused. Bring any preapproval with you so the terms can be compared side by side.
Can I start a Mazda finance application online from Palm Desert or Indio?
Yes. Palm Springs Mazda has a secure online finance application, so you can begin from home anywhere in the Coachella Valley and then finish the details in person in Cathedral City. Have your income, employment, and residence information ready, along with trade-in and payoff details if you plan to trade a vehicle.
Is it smarter to finance a new Mazda or a Mazda Certified Pre-Owned model?
Neither is automatically better. A new Mazda may qualify for manufacturer finance offers and has the latest features, while a Mazda Certified Pre-Owned vehicle can lower the amount financed and still includes a manufacturer inspection and added coverage. Ask to see both with similar terms so you can compare total cost, not just the monthly payment.
0 comment(s) so far on How to Finance a Mazda for Your Next Drive